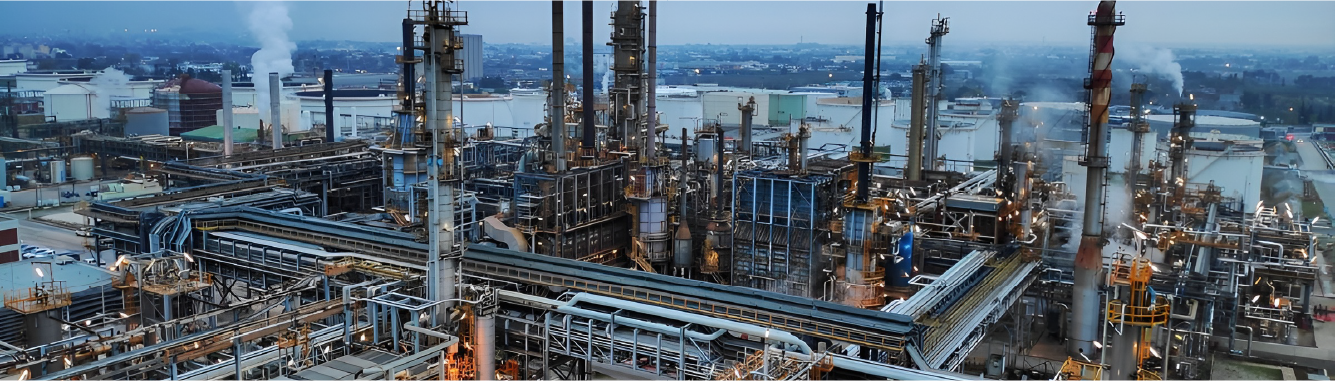
With refinery capacity expanding, new greenfield and brownfield projects progressing, and existing facilities becoming more complex, India is strengthening its position as a major refining and petroleum-products hub. The country’s installed refining capacity stood at approximately 267 million tonnes per annum (MMTPA) as of April 2026, according to India’s Petroleum Planning & Analysis Cell (PPAC).
But the significance of this expansion goes beyond capacity numbers. New investments are increasingly focused on higher-value products, petrochemicals, refinery integration, operational flexibility and import substitution. This is reshaping how India’s downstream oil & gas sector competes domestically and internationally.
From Refining Capacity to Downstream Competitiveness
India has been investing heavily in refining capacity to keep pace with rising domestic fuel and industrial demand.
From Refining Capacity to Downstream Competitiveness
India has been investing heavily in refining capacity to keep pace with rising domestic fuel and industrial demand.
Government projections have previously indicated that refinery capacity could reach around 309.5 MMTPA by 2028, supported by expansion projects at multiple public-sector refineries and new capacity additions.
The strategic shift, however, is not simply about adding barrels of processing capacity.
Modern refineries are increasingly being designed or upgraded to process a broader range of crude grades, improve conversion efficiency and produce products with greater commercial value. This allows operators to respond more effectively to changes in crude prices, product demand and regional market conditions.
For India, this creates a downstream sector that is increasingly positioned around flexibility, complexity and value creation rather than volume alone.
New Refinery Capacity Is Also About Petrochemicals
One of the most important changes taking place across India’s refining landscape is the closer integration of refining and petrochemical production.
New Refinery Capacity Is Also About Petrochemicals
One of the most important changes taking place across India’s refining landscape is the closer integration of refining and petrochemical production.
Traditional refinery economics have largely revolved around transportation fuels. But as demand patterns evolve and petrochemical consumption continues to grow, refiners are looking to extract greater value from every barrel of crude by increasing their production of polymers, aromatics and other chemical feedstocks.
IndianOil, for example, is targeting an increase in its Petrochemical Intensity Index from around 6.11% to 15% by 2030, alongside refinery and petrochemical investments.
The HPCL Rajasthan Refinery illustrates this direction. The 9 MMTPA refinery-cum-petrochemical complex is designed with a petrochemical product slate exceeding 26%, including polypropylene, polyethylene and aromatics.
This model can provide refiners with greater resilience when transportation-fuel margins weaken while demand for petrochemical products remains strong.
Brownfield Expansion Is Becoming a Major Growth Strategy
India’s downstream expansion is not being driven solely by new greenfield refineries.
Brownfield Expansion Is Becoming a Major Growth Strategy
India’s downstream expansion is not being driven solely by new greenfield refineries.
Existing facilities are also being upgraded through capacity debottlenecking, secondary processing units, residue upgrading, petrochemical integration and efficiency improvements.
Brownfield projects can provide a significant advantage because operators already have access to established infrastructure, logistics networks, utilities and distribution systems.
However, expanding an existing refinery also introduces considerable operational complexity. New processing units must be integrated with legacy systems without compromising reliability, safety or production continuity.
This makes effective project execution, asset integration and digital operational visibility increasingly important.
India’s Role as a Global Refined-Products Supplier
India’s refining expansion also has implications well beyond the domestic market.
India’s Role as a Global Refined-Products Supplier
India’s refining expansion also has implications well beyond the domestic market.
The country has developed a significant position as an exporter of petroleum products, supplying markets across Asia, Europe and other regions. Additional refining capacity and higher refinery complexity can support India’s ability to respond to international product-market opportunities.
This role becomes particularly important when supply disruptions affect major refining centres elsewhere.
However, the relationship between domestic demand and exports will remain critical. As Indian fuel consumption grows, refiners will need to balance domestic supply requirements with export opportunities.
The result could be a more dynamic downstream market in which Indian refiners continuously optimize production according to domestic demand, international margins, crude economics and regional supply conditions.
Infrastructure Must Keep Pace With Refining Growth
Refinery expansion cannot be viewed in isolation.
Infrastructure Must Keep Pace With Refining Growth
Refinery expansion cannot be viewed in isolation.
Additional processing capacity requires supporting infrastructure across the downstream value chain—including crude import terminals, pipelines, storage, product terminals, transportation networks and petrochemical logistics.
The growth of refining capacity therefore has a multiplier effect on India’s wider industrial infrastructure.
Ports and crude-handling facilities need to accommodate changing import requirements. Pipeline networks must support greater movement of crude and products. Storage infrastructure needs to provide sufficient flexibility to manage supply fluctuations.
The downstream expansion story is consequently becoming an integrated infrastructure story.
What India’s Refining Expansion Means for the Downstream Sector
What India’s Refining Expansion Means for the Downstream Sector
India’s growing refining capacity is reshaping the downstream oil & gas landscape at multiple levels.
It is strengthening domestic product availability, supporting petrochemical growth, creating new export opportunities and encouraging investment across associated infrastructure. At the same time, it is raising the bar for operational efficiency, digital integration and refinery flexibility.
The next phase of India’s downstream growth will therefore not be defined simply by how many million tonnes of crude the country can process.
It will be defined by how intelligently that capacity is operated, how much value is extracted from each barrel, and how effectively refining is integrated with India’s wider industrial and petrochemical economy.
As new projects come online and existing refineries become more sophisticated, India has an opportunity to strengthen its position as one of the world’s most strategically important refining and downstream markets.
Categories
Downstream Oil & Gas